

How a $2 Million CDTFA Sales Tax Assessment Was Reduced to $38,000
On: October 14, 2026
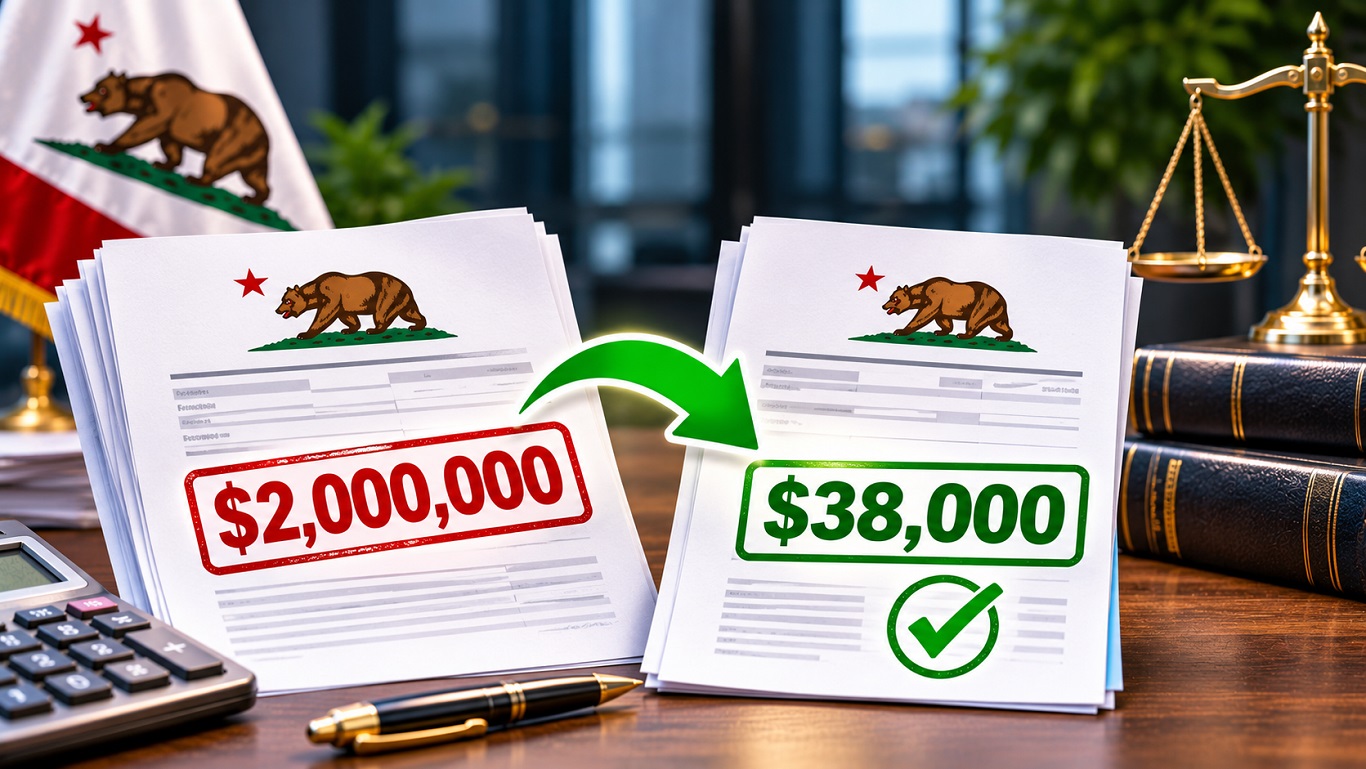
Table of Contents
- Overview: Challenging a $2 Million California Sales Tax Assessment
- The Challenge: A Significant CDTFA Tax Assessment
- How Can a California Sales Tax Assessment Be Challenged?
- The Reported Outcome: From $2 Million to $38,000
- Why CDTFA Audit Representation Matters?
- What Can Businesses Learn From This Case?
- Facing a Large California Sales Tax Assessment?
- Frequently Asked Questions About CDTFA Sales Tax Audits
Practice Area: California Sales Tax Audit Representation
Tax Authority: California Department of Tax and Fee Administration (CDTFA)
Reported Initial Assessment: $2,000,000
Reported Final Assessment: $38,000
Reported Reduction: $1,962,000 (98.1%)
Attorney: Elizabeth Nelson, Esq.
Firm: Leading Tax Group
Overview: Challenging a $2 Million California Sales Tax Assessment
A California sales tax audit can create significant financial pressure for a business, particularly when the California Department of Tax and Fee Administration (CDTFA) issues a substantial tax assessment. An assessment of this size can affect cash flow, business operations, financial planning, and the owner’s ability to meet ongoing obligations.
In one reported case handled by Leading Tax Group, a CDTFA sales tax assessment of approximately $2 million was reduced to $38,000. The result represents a reported reduction of $1,962,000, or approximately 98.1% of the original assessment.
The case is a notable example of the potential importance of challenging a significant sales tax assessment rather than automatically accepting the initial amount. The outcome was documented in Leading Tax Group’s tax controversy success-story records and is associated with the firm’s work in California sales tax matters.
Although the available case summary does not identify the business or explain the specific audit adjustments that led to the reduction, the reported result demonstrates why businesses facing substantial CDTFA liabilities should understand their options for reviewing and disputing audit findings.
The Challenge: A Significant CDTFA Tax Assessment
The CDTFA administers California’s sales and use tax laws and conducts audits to determine whether businesses have correctly reported and paid their tax obligations. An audit may involve reviewing sales records, purchase transactions, deductions, exemption documentation, accounting records, and sales tax returns.
When an audit identifies discrepancies, the resulting assessment may include additional tax, interest, and applicable penalties. The amount assessed can be substantial, especially when the disputed transactions cover multiple reporting periods or when the available records do not clearly support the business’s original tax reporting.
For a business facing a $2 million assessment, determining how the CDTFA calculated the amount is an important part of evaluating the dispute. The taxpayer needs to understand which transactions were questioned, which records were considered, and how the audit findings were translated into the proposed or final liability.
In this case, Leading Tax Group’s records report that the initial $2 million assessment was ultimately reduced to $38,000. However, the available summary does not establish which transactions, deductions, reporting issues, or legal arguments were involved.
How Can a California Sales Tax Assessment Be Challenged?
A CDTFA assessment should be evaluated against the applicable tax laws, the business’s records, and the specific findings documented in the audit. The appropriate response depends on the facts of the case, the procedural stage, and the available evidence.
A detailed sales tax audit review may involve examining sales and purchase records, reconciling reported revenue with accounting data, reviewing exemption certificates, evaluating taxable and nontaxable transactions, and checking the calculations supporting the assessment.
California’s published audit procedures also provide for communication about audit findings, access to audit working papers, and opportunities to submit additional information for consideration. Businesses that disagree with audit conclusions may have administrative review and appeal options, subject to applicable requirements and deadlines.
These are general elements of California sales tax audit defense, not a description of the specific steps taken in this case. The available success-story record does not identify the arguments, supporting documents, negotiations, or procedural actions responsible for the reported reduction.
The Reported Outcome: From $2 Million to $38,000
According to Leading Tax Group’s documented success stories, the CDTFA assessment was reduced from $2,000,000 to $38,000.
The financial difference is substantial:
- Original assessment: $2,000,000
- Reported final assessment: $38,000
- Reported reduction: $1,962,000
- Percentage reduction: Approximately 98.1%
This means the reported final assessment was approximately 1.9% of the original amount.
For a business facing a major tax controversy, a reduction of this scale can materially change the financial implications of the dispute. Nevertheless, the final amount should not automatically be interpreted as a complete elimination of the underlying tax liability or as confirmation that every component of the assessment was removed.
The available record does not specify whether the original amount included tax, interest, penalties, or a combination of these components. It also does not explain the final payment terms or whether any additional obligations remained.
The documented result should therefore be understood as a reported reduction in the assessment, rather than a guarantee that similar reductions are available in other cases.
Why CDTFA Audit Representation Matters?
Businesses responding to a California sales tax audit must consider both the substantive tax issues and the procedural requirements involved in challenging an assessment.
Professional CDTFA audit representation can help a business understand the audit findings, organize supporting records, evaluate disputed transactions, communicate with the agency, and assess available review or appeal options. Depending on the case, the review may also identify reporting errors or documentation gaps that require attention.
California’s audit procedures recognize the importance of records in determining the correct tax liability. Relevant documentation may include sales invoices, purchase records, general ledgers, bank records, exemption certificates, resale documentation, point-of-sale data, and the schedules used to prepare sales and use tax returns.
When the assessment is disputed, a structured review can help identify which issues require further evidence, which calculations need examination, and which procedural options may be available.
Leading Tax Group offers CDTFA audit representation and California tax resolution services for businesses dealing with sales tax disputes and related collection concerns. The specific approach in any matter should be based on the taxpayer’s records, the agency’s findings, and the applicable law.
What Can Businesses Learn From This Case?
This reported outcome highlights several considerations for businesses facing substantial California sales tax assessments.
- First, review the assessment carefully. An initial assessment should be examined alongside the audit findings and supporting calculations. Understanding how the agency reached its conclusion is essential to evaluating a dispute.
- Second, preserve relevant business records. Sales invoices, purchase records, exemption certificates, accounting data, and electronic transaction records can help substantiate reported figures and explain differences identified during an audit. Businesses should retain records for the applicable period and throughout any ongoing dispute.
- Third, understand available review options. If a business disagrees with the audit results, it should promptly evaluate the applicable response deadlines and administrative procedures. Missing a deadline may affect the available options.
- Finally, obtain case-specific guidance. The appropriate response depends on the assessment’s basis, the available documentation, the procedural stage, and the applicable legal requirements. A result achieved in one case does not establish the likely outcome of another.
Facing a Large California Sales Tax Assessment?
A substantial CDTFA assessment can leave business owners uncertain about their next steps. Understanding the audit findings, reviewing the supporting records, and evaluating the available resolution options can help clarify the path forward.
Leading Tax Group provides CDTFA audit representation and California tax resolution support for businesses dealing with disputed assessments and sales tax liabilities.
Contact Leading Tax Group to discuss your CDTFA audit, review your tax assessment, and understand the options that may be available for your business.
Frequently Asked Questions About CDTFA Sales Tax Audits
Can a $2 million CDTFA assessment be reduced?
Yes. A CDTFA assessment may be reduced when the audit findings, supporting evidence, applicable law, or subsequent review justify an adjustment. In this reported Leading Tax Group case, the assessment was reduced from $2 million to $38,000. The result is specific to that case and does not guarantee a similar reduction for other businesses.
What records are important during a California sales tax audit?
Relevant records may include sales invoices, purchase receipts, general ledgers, bank statements, resale certificates, exemption documentation, point-of-sale reports, and sales tax returns. The required records depend on the transactions and issues being examined. Businesses should retain relevant records throughout an ongoing audit or dispute.
Can a business dispute CDTFA audit findings?
Yes. Businesses may have options to submit additional information, request administrative review, or pursue an appeal when they disagree with CDTFA audit findings. The available procedure and applicable deadlines depend on the notice and the stage of the case. A business should review the relevant correspondence promptly.
Does a reduced assessment mean the business owes no tax?
No. A reduction does not necessarily eliminate the remaining liability. In this case, the reported assessment was reduced to $38,000, not zero. The available success-story record does not explain the composition of the final amount or whether further payment arrangements or obligations applied.
 800-900-4250


